Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
The rapid market share gains of Chinese electric vehicles in Europe pose a significant risk to the continent's automotive supply chain. Since Chinese OEMs often use cheaper, domestic components, they can shrink the total addressable market for premium Western suppliers like Seeing Machines, even as total vehicle sales grow.

Related Insights
Chinese companies are circumventing potential EU tariffs by establishing manufacturing plants within Europe, particularly in the auto and green tech sectors. This FDI strategy, mirroring Japan's 1980s U.S. expansion, bypasses import duties, intensifies local competition, and renders traditional trade barriers less effective.

Intended to help struggling European automakers, the EU's decision to relax its ban on petrol cars creates a vulnerability. This policy shift may inadvertently benefit Chinese manufacturers, whose popular hybrid vehicles are gaining significant market share in Europe and are not subject to the same hefty tariffs as pure EVs.
The primary threat to Japan's auto industry is the rapid rise of Chinese competitors. While Japanese firms were skeptical of EVs, Chinese companies came to dominate electric vehicle technology, enabling them to produce cars more quickly and cheaply, rapidly eroding Japan's market share.
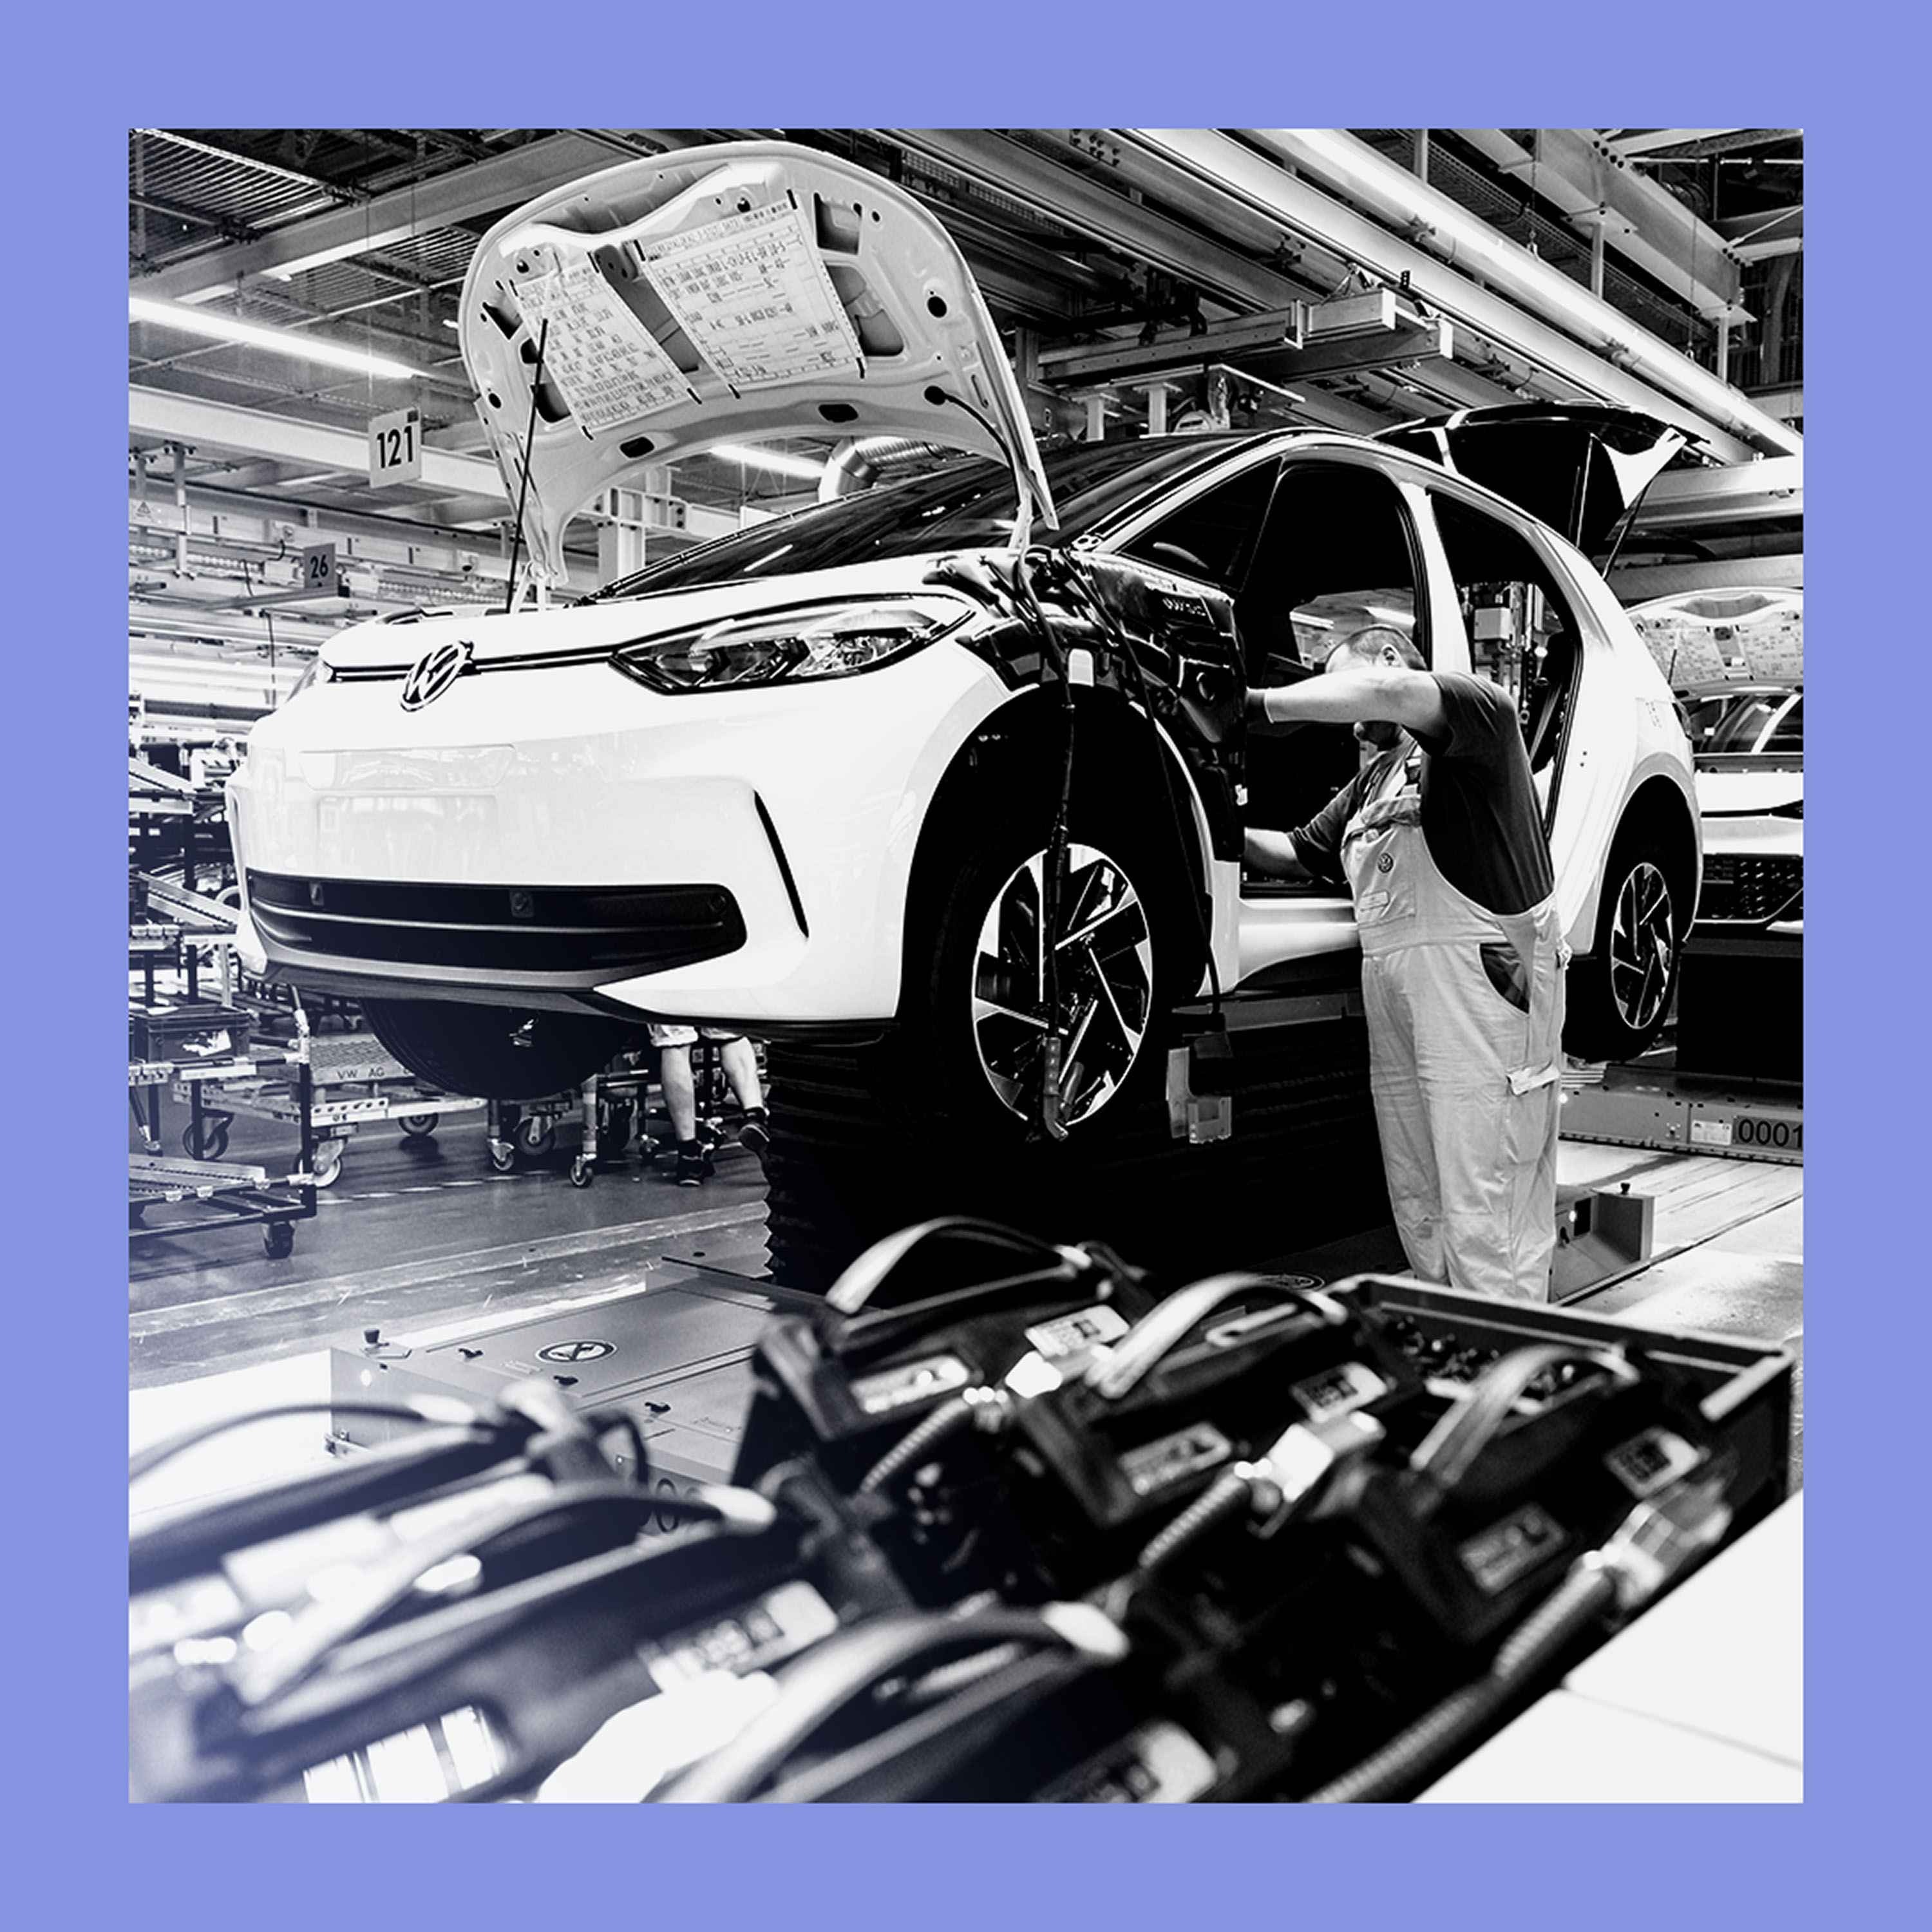
German automaker Volkswagen can now develop and build an electric vehicle in China for half the cost of doing so elsewhere. This shift from simple manufacturing to localized R&D—the "innovate in China for the world" model—signifies a dangerous hollowing out of core industrial capabilities and high-value jobs in Western economies.

While the influx of Chinese EV brands like BYD into Europe gets attention, the greater financial damage to European manufacturers comes from losing market share within China itself. Chinese consumers are increasingly choosing local brands out of national pride, eroding a once-lucrative export market for companies like Porsche.

Despite overtaking Tesla, BYD's growth faces significant threats. Domestically, China is reducing EV purchase tax exemptions, potentially dampening demand. Globally, the influx of cheap Chinese EVs is likely to trigger protectionist trade barriers in key markets like the EU, limiting export growth.

While headlines focus on advanced chips, China’s real leverage comes from its strategic control over less glamorous but essential upstream inputs like rare earths and magnets. It has even banned the export of magnet-making technology, creating critical, hard-to-solve bottlenecks for Western manufacturing.
The Nexperia dispute reveals China's strategic leverage. By controlling the supply of mid-tech chips for basic car functions like airbags and windows, Beijing can cripple major European automakers, demonstrating its influence over global supply chains beyond just high-end tech.
A persistent headwind for European markets is the dual impact of rising Chinese competition and weak demand from China. For the past several years, this single factor has been responsible for a staggering 60% to 90% of all earnings downgrades across the European index, particularly hitting sectors like chemicals and autos.

European automakers, heavily invested in combustion engines and hampered by regulations that stifle new entrants, are ill-equipped to compete with China's cheaper, superior electric vehicles. This creates an existential threat to a cornerstone of Europe's industrial economy.