Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
Rocket Lab strategically avoids becoming a 'moon company' because shifting government priorities (Moon vs. Mars) create financial havoc. By providing components and systems to lunar programs instead, they participate in the upside while insulating themselves from the financial whiplash of changing mission goals.

Related Insights
Despite expanding ambitions, NASA's budget has been effectively flat in real terms since the post-Apollo era. This constraint forces the agency to partner with and leverage the private sector to achieve costly goals like returning to the moon and exploring Mars.

Beyond financing, Peter Beck's personal motivation for the IPO was to instill extreme discipline and create a structure that could outlast its founder. He sees going public as a mechanism to ensure the company's impact continues, avoiding the fate of founder-centric private companies.
Companies like Phantom Space build their own rockets not just for cost, but as a strategic necessity. The aerospace supply chain is inadequate, and relying on competitors like SpaceX for launch services is untenable as they prioritize their own constellations, effectively cutting off rivals from accessing space.

By acquiring Iridium, Rocket Lab gains a mature satellite network, valuable spectrum, and a customer base. This shift from a niche launch provider to an integrated space powerhouse is a direct challenge to SpaceX's dominance in the space applications market, proving vertical integration is the core strategy.
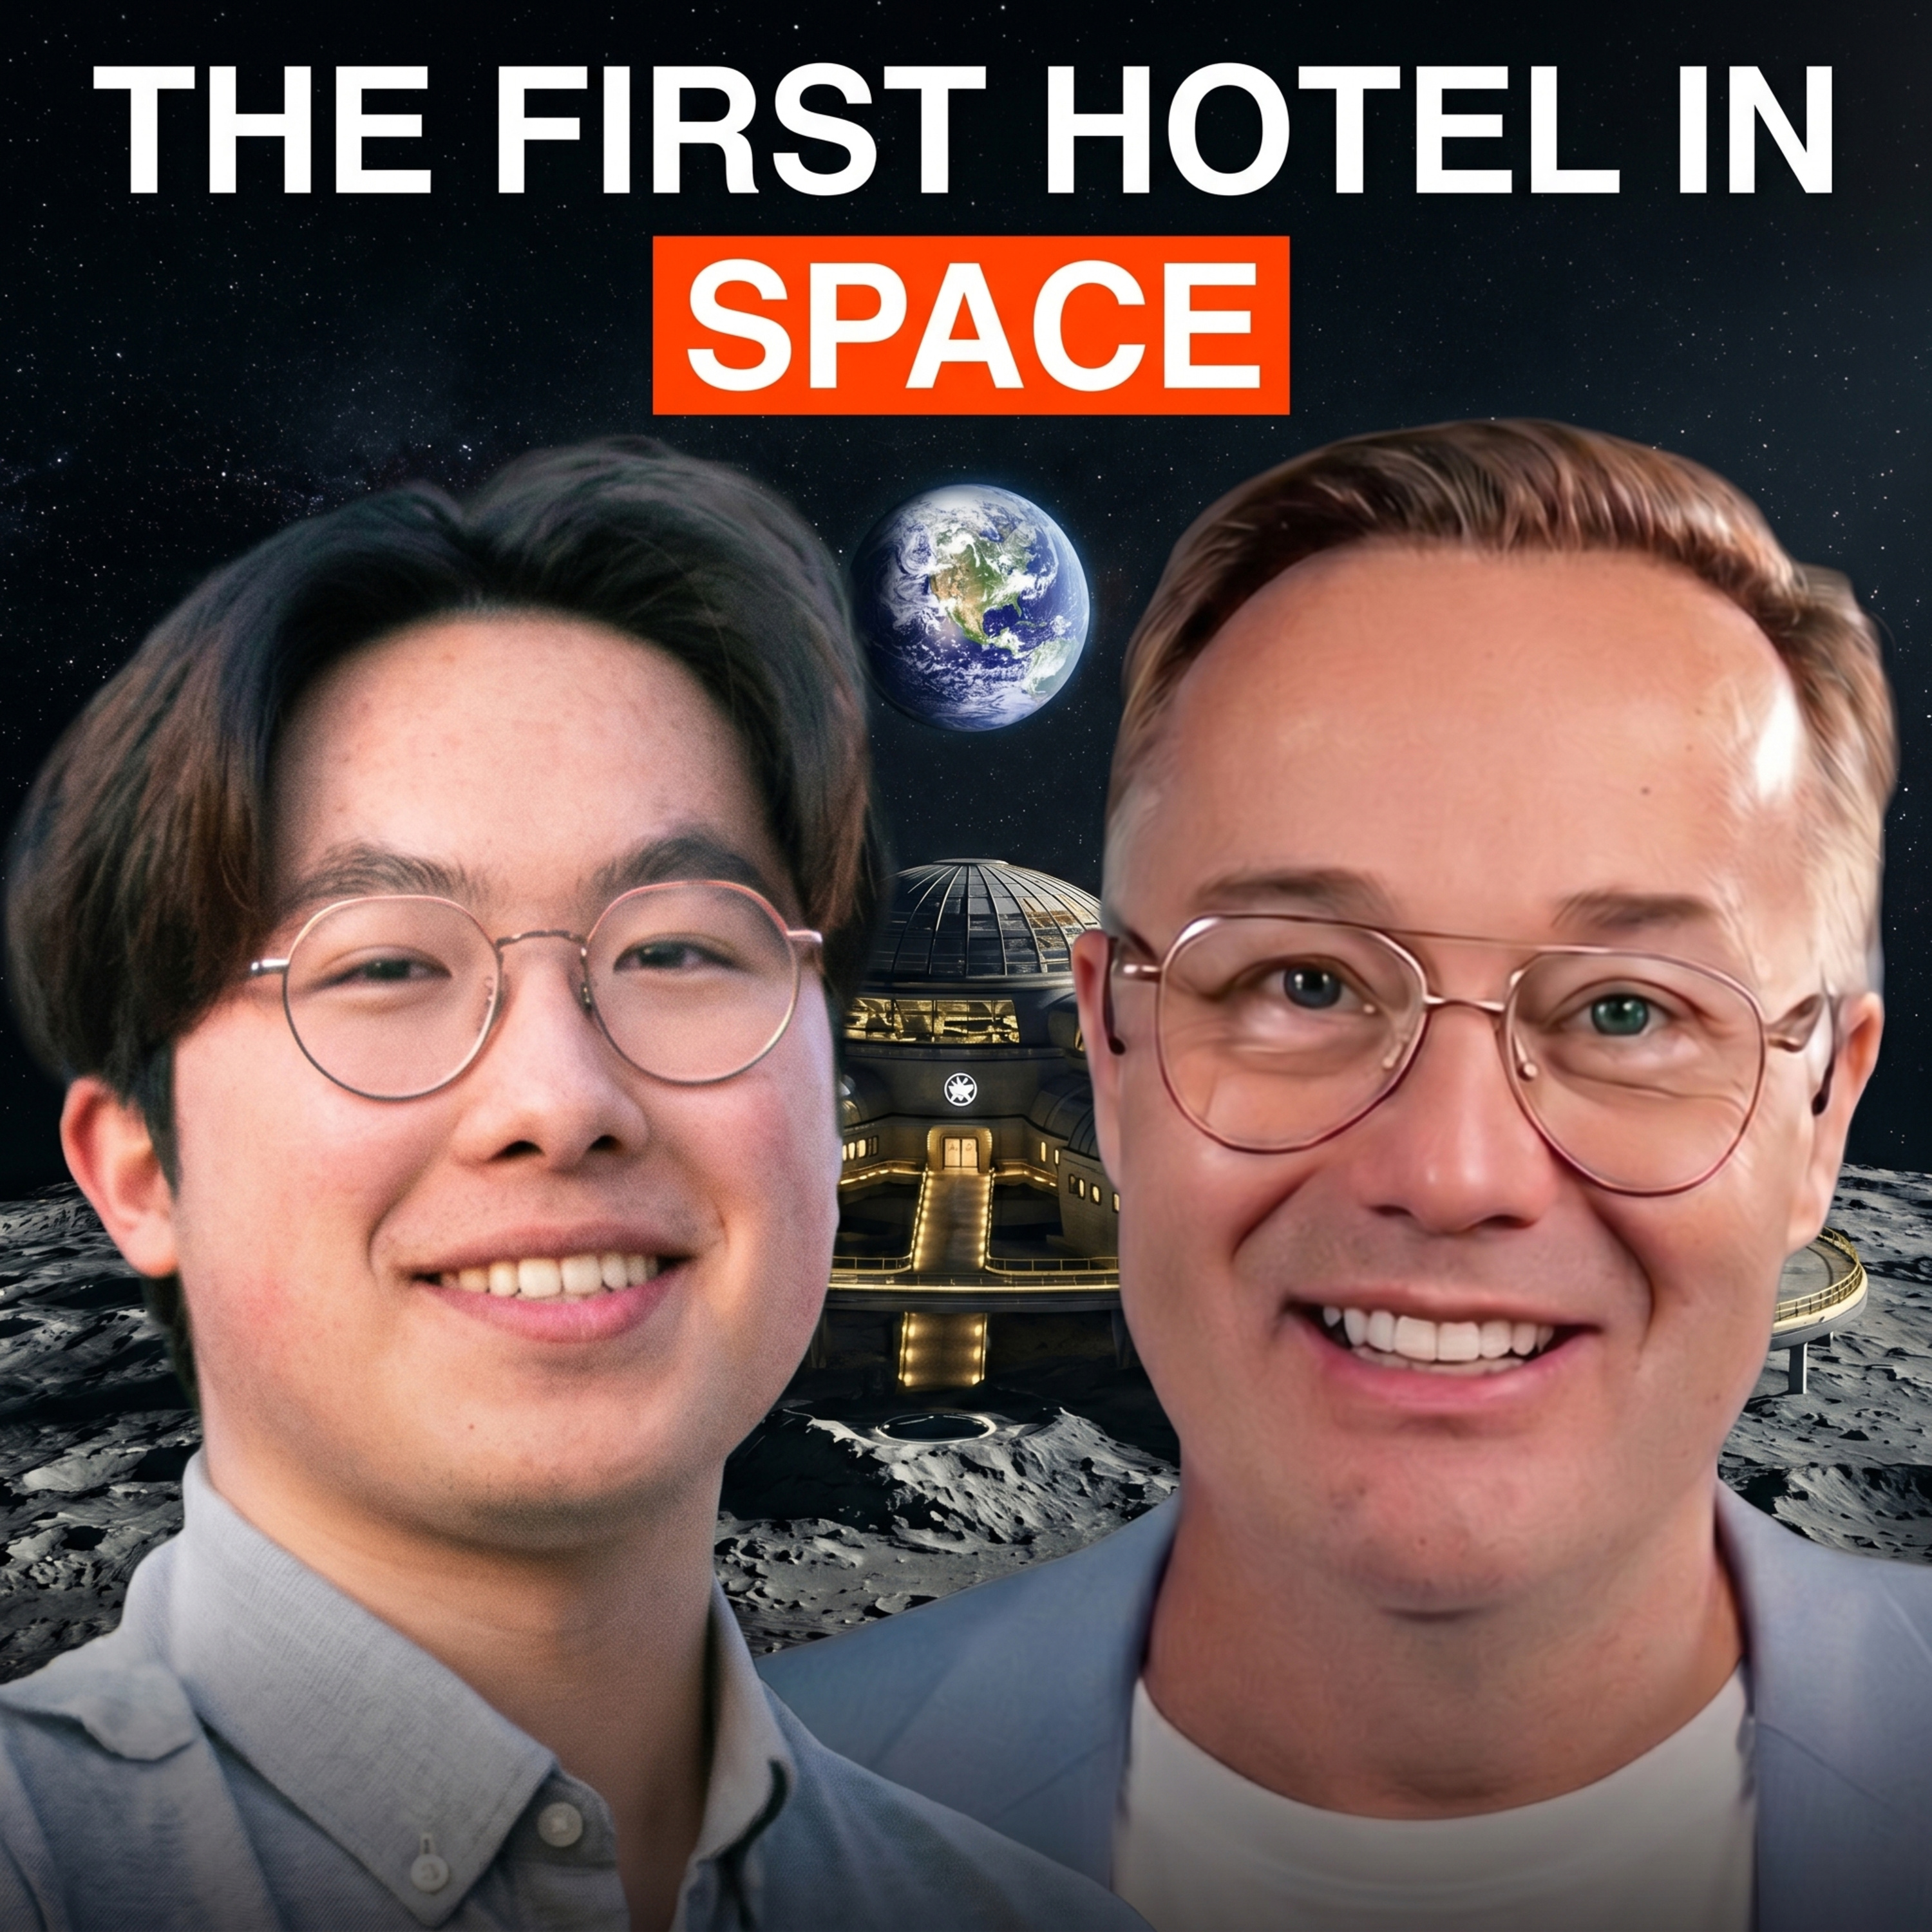
GRU Space's strategy is to build a commercial moon hotel to create demand for lunar services, positioning them as the go-to contractor for NASA's larger moon base projects. This creates a private ecosystem, reducing reliance on government funding.
NASA is explicitly rejecting grand, single-shot proposals for a fully-formed moon base. Instead, the agency will use a step-by-step process, starting with smaller landers and rovers to build capabilities iteratively. This signals a shift toward a more agile and risk-managed procurement strategy for government contractors.

Frame moonshot projects like Google's Waymo not as singular bets, but as platforms for innovation. Even if the primary goal fails, the project should be structured to spin off valuable 'side effects'—advances in component technologies like AI, mapping, or hardware that benefit the core business.
SpaceX is strategically delaying its Mars ambitions to first establish a permanent, 'self-growing' city on the moon. Elon Musk now views this as a more practical 10-year goal, with the moon serving as an essential staging ground for materials and deeper space exploration, rather than a direct-to-Mars approach.

Elon Musk has strategically shifted SpaceX's primary focus from colonizing Mars to establishing an industrial base on the Moon. The new vision is to manufacture AI satellites on the lunar surface and launch them into a 'Dyson swarm' using electromagnetic mass drivers, framing the Moon as a critical stepping stone for a space-based economy.
For the Artemis program, NASA is not building and owning lunar landers as it did during Apollo. Instead, it is contracting SpaceX and Blue Origin to provide landing as a managed service. This marks a fundamental shift from asset ownership to a services-based procurement model.