Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
Unlike past bubbles driven by single factors like credit, tech, or real estate, the current AI moment uniquely sits at the intersection of all major historical bubble ingredients simultaneously: loose credit, a great technology story, a real estate component (data centers), and a policy angle.

Related Insights
Unlike past speculative bubbles, the current AI frenzy has near-universal, top-down support. The government wants domestic investment, tech giants are in a competitive spending arms race, and financial markets profit from the growth narrative. This rare alignment of interests from all major actors creates a powerful, self-reinforcing mandate for the bubble to continue expanding.

Unlike past bubbles (e.g., railroads), today's investors explicitly justify AI overspending by citing the eventual positive outcomes of prior bubbles. This creates a self-reinforcing, reflexive loop that encourages even greater excess than was seen in previous historical cycles.

Unlike past bubbles driven purely by market mania, the current AI boom is sustained by supportive fiscal and monetary policy. This makes it more resilient and dependent on policy shifts, rather than just market sentiment, for a correction.

The current AI boom follows Schumpeter's classic model of technological change: massive, credit-fueled overinvestment causes a boom. This will be followed by a bust and recession as the new technology displaces old industries and most AI firms fail. Only then will the technology fully permeate society during the subsequent slump.
The current AI spending frenzy uniquely merges elements from all major historical bubbles—real estate (data centers), technology, loose credit, and a government backstop—making a soft landing improbable. This convergence of risk factors is unprecedented.

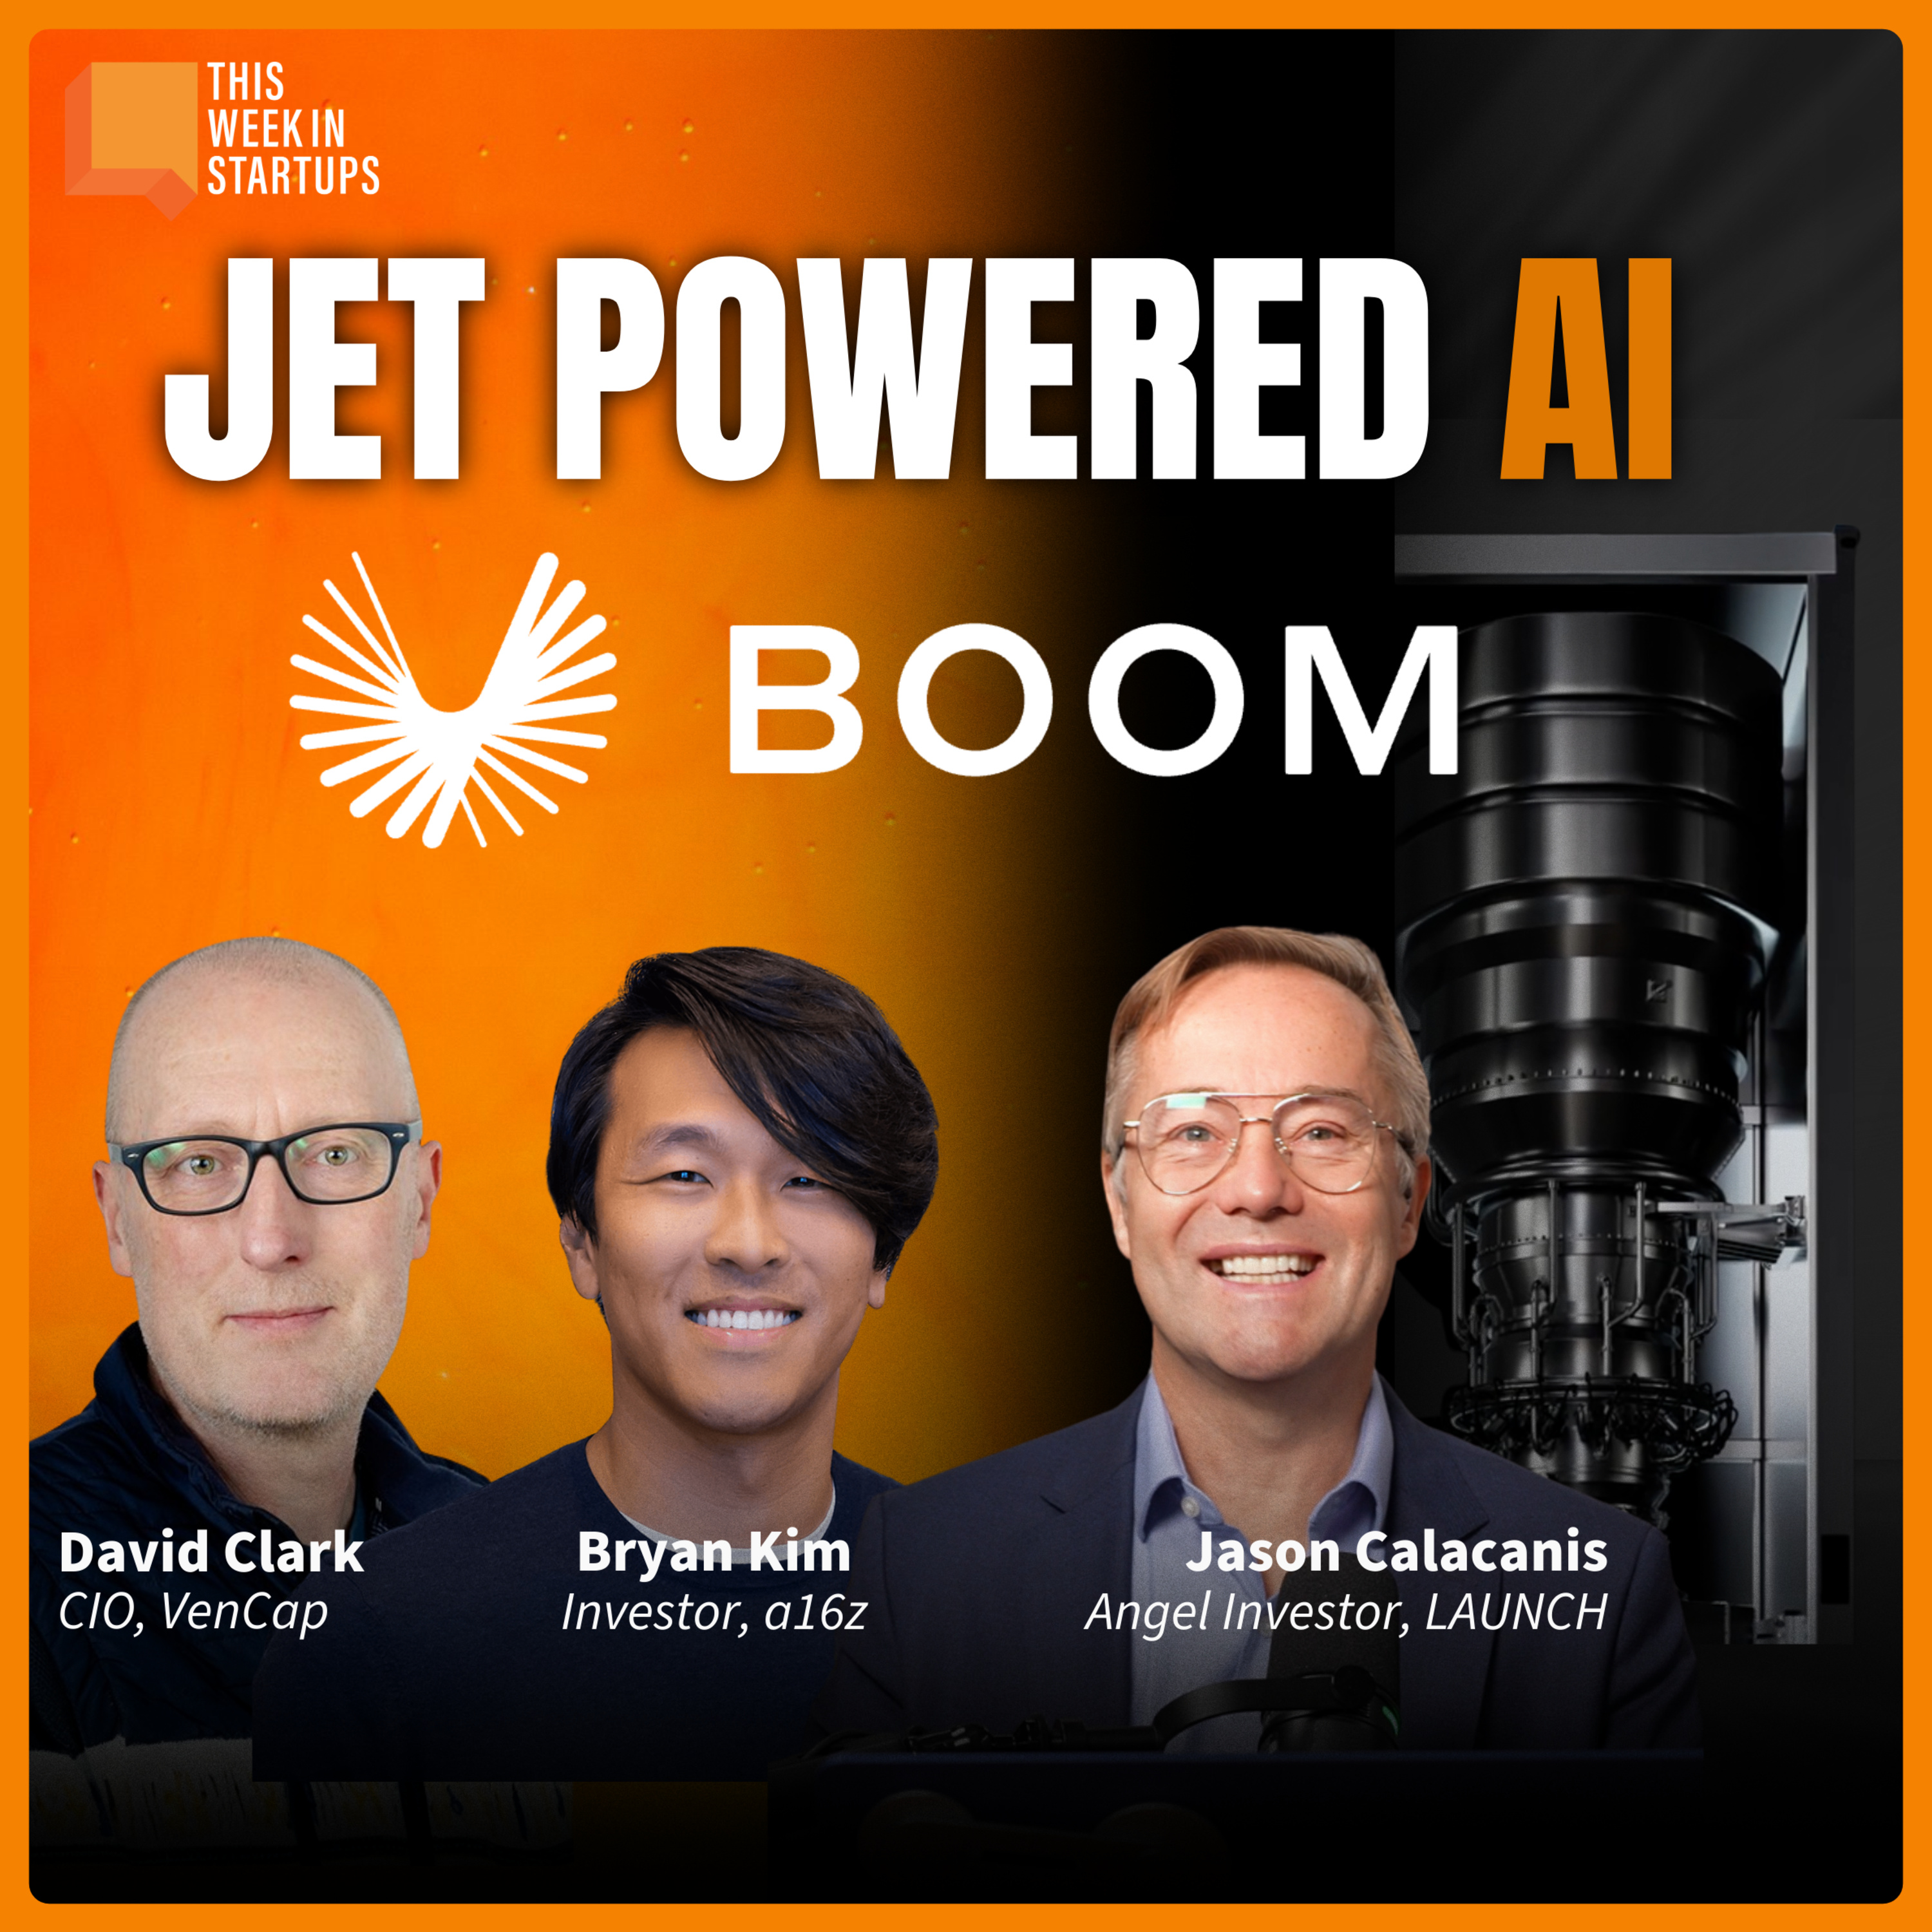
Vincap International's CIO argues the AI market isn't a classic bubble. Unlike previous tech cycles, the installation phase (building infrastructure) is happening concurrently with the deployment phase (mass user adoption). This unique paradigm shift is driving real revenue and growth that supports high valuations.
Grant believes the excitement and capital influx into AI dwarfs the 1990s internet boom. He argues it's fueled by a speculative spirit and potential miscalculations of supply and demand, much like past technological manias, rather than by sound analysis.
Unlike previous tech cycles, the current AI expansion relies heavily on cheap debt financing by hyperscalers. A credit market crisis, potentially triggered by geopolitical instability, could choke off this funding and cause a sharp, widespread correction in the AI sector.

Economic cycles are characterized by the corporate bond market funneling excessive capital into a single hot sector, creating a boom-bust cycle. This pattern was seen in housing (2008) and commodities (2015), and is now repeating with the AI infrastructure buildout.
Marks argues that speculative bubbles form around 'something new' where imagination is untethered from reality. The AI boom, like the dot-com era, is based on a novel, transformative technology. This differs from past manias centered on established companies (Nifty 50) or financial engineering (subprime mortgages), making it prone to similar flights of fancy.
