Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
Terry Wiseman of Macquarie says rising French bond yields signal doubt over deficit control. Market pressure prompts spending cuts, which call protesters out demanding more spending. Street unrest then hurts GDP and tax revenue, putting more pressure on bonds; he calls it a doom loop.

Related Insights
Despite the ECB's powerful TPI backstop, it's unlikely to be used for France. Market turmoil there is driven by fundamental concerns over France's own lack of fiscal consolidation, not an external shock. This highlights a crucial limit of central bank intervention: safety nets are not designed to solve domestic political and fiscal failures.

While fiscal deficits are common across developed markets, France faces surging bond spreads over Germany because of the large gap between sluggish GDP growth and high borrowing costs. Investors demand a higher risk premium when ongoing political dysfunction blocks credible deficit reduction and projected debt servicing costs significantly outpace national output expansion.

Unlike political pressure or stock market volatility, a sell-off in the government bond market forces fiscal discipline by directly increasing a nation's borrowing costs. This financial pain acts as a powerful, non-negotiable catalyst for governments to address unsustainable spending and debt, as seen in Greece and the UK.

French debt market stress is not driven by unanticipated fiscal deterioration, as France has run structural deficits for decades. Instead, investors are repricing political risk, fearing that even a presidential victory by Marine Le Pen in 2027 will lead to a fractured, ungovernable parliament incapable of passing budgets.

A self-reinforcing cycle of high government spending, lagging tax receipts, and rising interest expenses forces the Treasury to issue more debt. This "doom loop" continuously adds to the supply of bonds, putting structural upward pressure on long-end yields.

Watching the spread between French bonds and German Bunds reveals specific sovereign financial stress driven by political deadlocks and stubborn budget deficits. A widening gap signals institutional and fiscal fracturing within the Eurozone well before broad macroeconomic headline figures capture the deterioration.

French 10-year yields have widened to around 150 basis points over German Bunds, touching levels reminiscent of the 2011 European sovereign debt crisis. Because France faces heavy 5% to 6% budget deficits and potential fiscal austerity under Maastricht Treaty limits, tight monetary policy risks fracturing the eurozone, creating severe macro risks that equity markets have yet to fully price.

Chamath explains that rising debt-to-GDP ratios force institutional debt buyers to raise long-term yields to compensate for perceived sovereign risk. This pressure forces immediate fiscal austerity in vulnerable European economies and risks spilling over to tighten capital conditions in the United States.

Secondary school demonstrations in France began over narrow, operational issues like exam formatting, facility disrepair, and teacher absences. However, the movement rapidly surged to over 250,000 protesters because it absorbed deep national anxiety. With a 5% budget deficit, bond market pressure demanding spending cuts, and an impending presidential election, local school dissatisfaction became an outlet for wider political tension and resistance to government austerity.
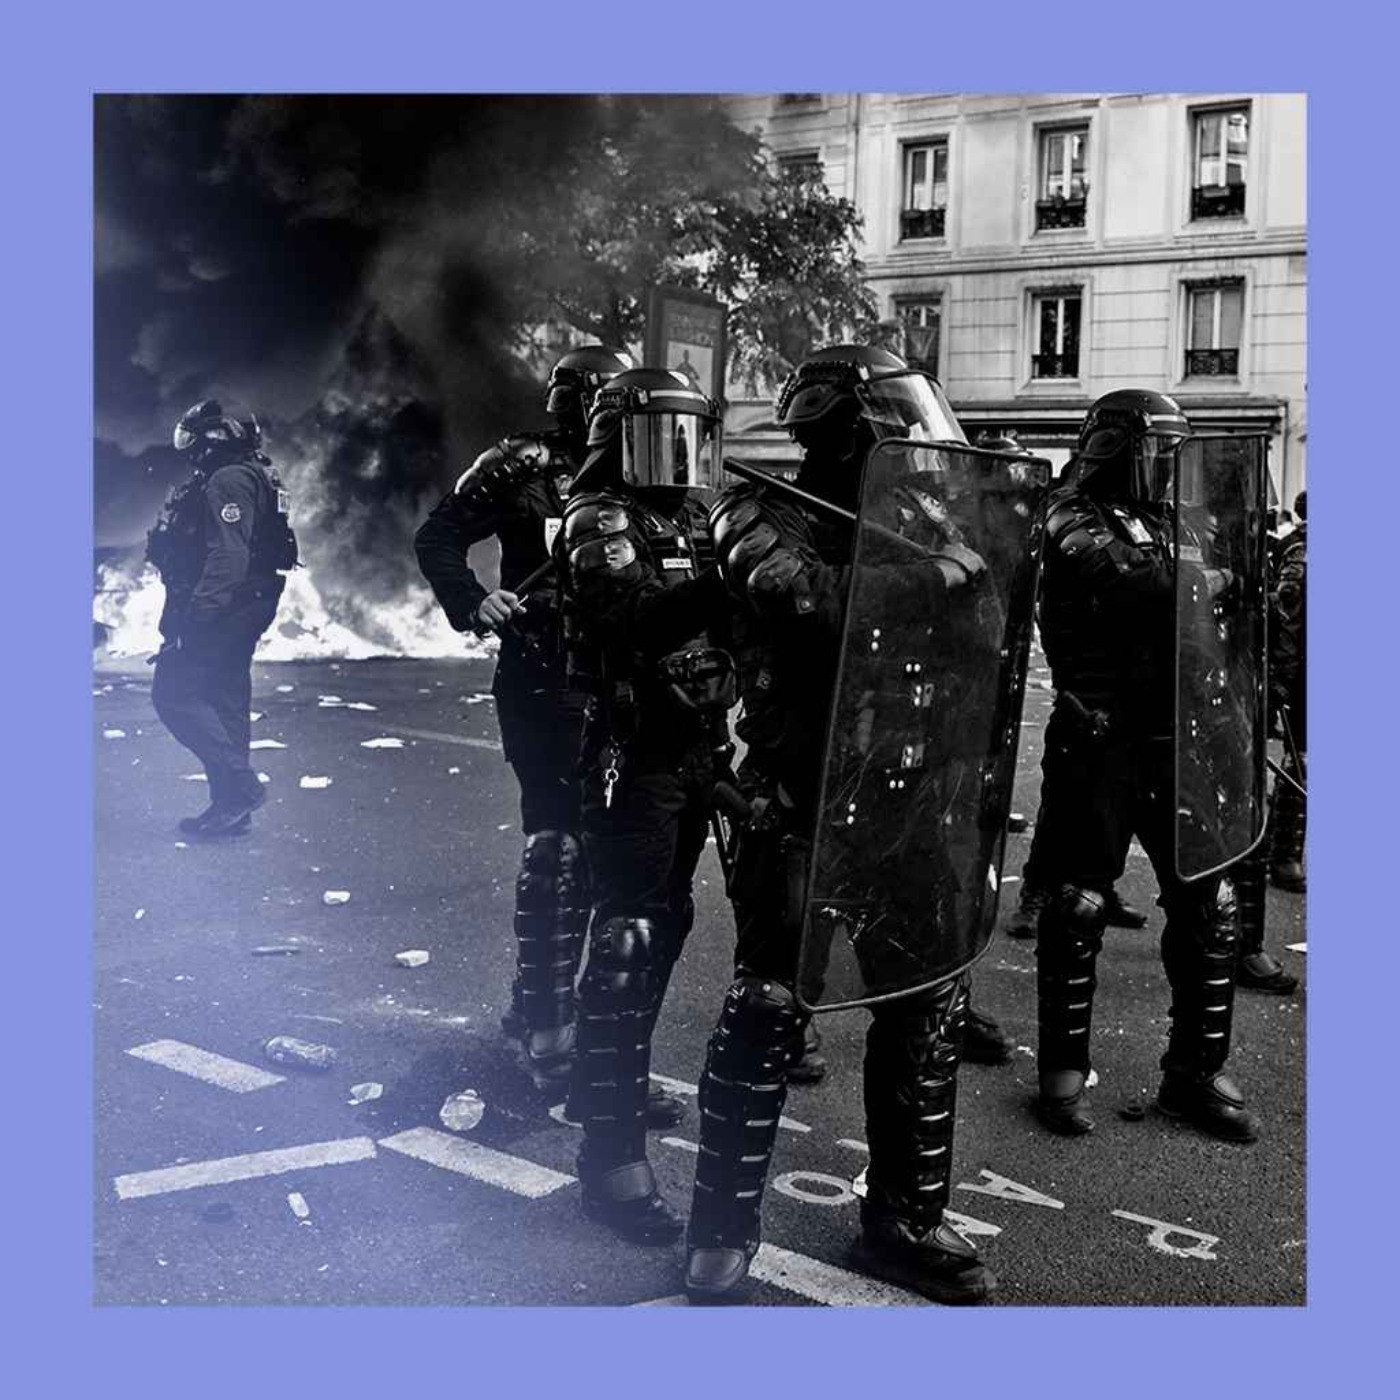
Tom notes French public spending is 57% of GDP and one in five workers is a civil servant. Reform means a visible income hit to millions of organized people who are ready to march and burn, while future beneficiaries like young workers are scattered and voiceless.
