Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
Chinese products generally debut at a 30 percent discount, but prices typically rise over subsequent years due to product upgrades. While discounts against incumbents stay fairly stable, aggressive price cutting is usually initiated later by struggling local incumbents attempting to defend lost market share.

Related Insights
Western pharmaceutical companies are no longer seeking cheap 'me-too' assets in China. Instead, they are paying premium prices for genuinely innovative drugs, as evidenced by a 10x increase in deal size over five years and a surge in patent filings from the region.

Established global companies frequently dismiss low-margin tiers to protect high-margin customers when Chinese competitors arrive. This seemingly logical resource allocation acts as a trap by granting foreign challengers an uncontested beachhead in underserved segments from which they migrate upmarket.
China's harsh, deflationary economic environment and intense domestic competition, while causing many companies to fail, effectively hones a select few into highly resilient and efficient champions. These survivors are now prepared for successful global expansion.
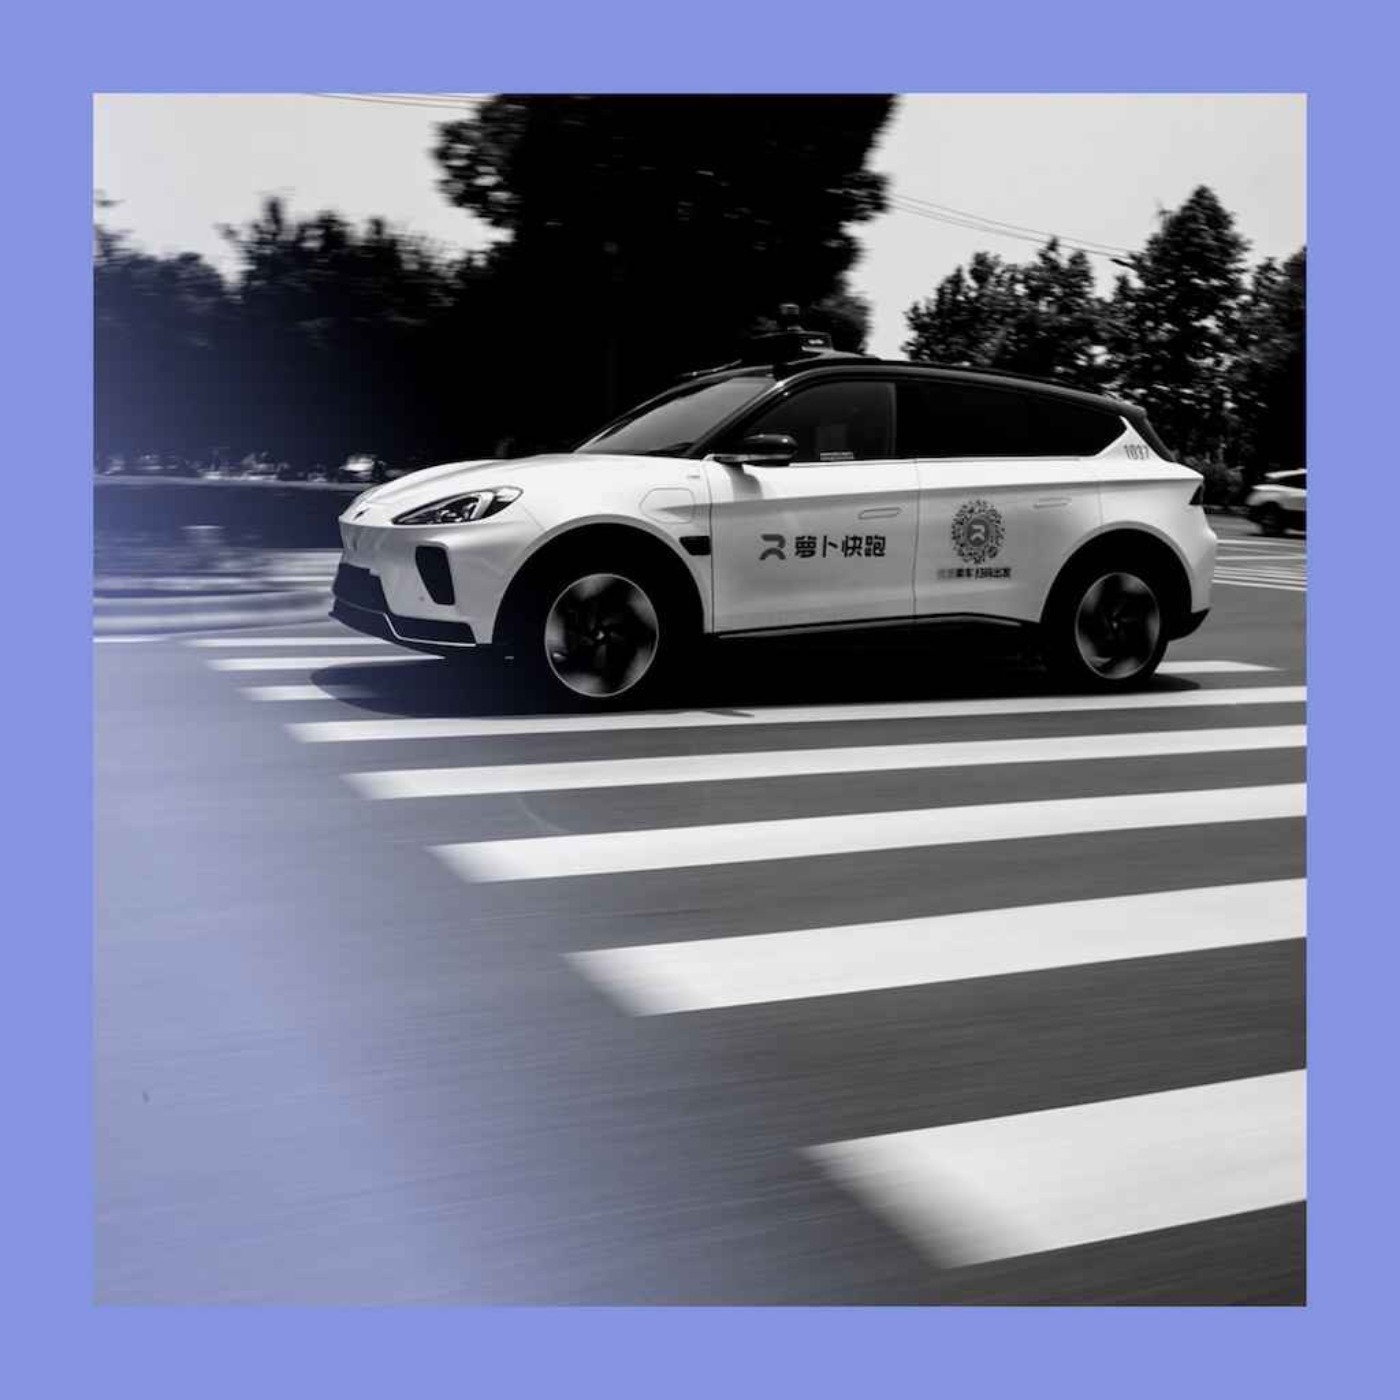
Chinese competitors capture market share swiftly in modular, consumer-facing categories, but face steep barriers against interconnected B2B products. Extensive full-lifecycle maintenance networks, capital-intensive physical distribution channels, and decades of earned customer trust provide durable defensibility against new entrants.
With at least 60 producers launching some 500 models in a year, China's domestic EV market is intensely competitive. This environment acts as a 'fittest gym', producing technologically advanced and price-competitive companies that are formidable global players when they export.
China's economy presents a stark contrast: a collapsing domestic property market versus a remarkably resilient export sector. Despite tariffs, exports remain strong because China continues to improve product quality and price competitiveness, maintaining global manufacturing dominance.

Public markets ruthlessly penalize incumbent firms, slashing market caps by 50 to 80 percent following modest market share losses. Simultaneously, investors remain deeply skeptical of Chinese corporate expansion, assigning valuations below one-times projected sales over profitability concerns and trade friction risks.
For the first time, a major Chinese automaker (BYD) is selling more cars abroad than in its hypercompetitive home market. This critical milestone demonstrates that Chinese industrial giants can successfully pivot to global markets to escape intense domestic price wars, setting a precedent for other sectors.

China uses a systematic four-step process to dominate industries. First, it subsidizes over 100 entrants. Second, it allows intense domestic competition to find the strongest. Third, it consolidates all subsidized manufacturing capacity under the few winners for free. Finally, it unleashes these champions to conquer global markets.

Contrary to the belief that cheaper technology levels the playing field, it often benefits established companies most. These incumbents can leverage the now-cheaper tool to enhance their existing products and reach more customers. New startups built solely on the cheap tool often fail because they lack a unique business foundation and are easily copied.
