Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
M&A has a bad reputation because high-profile, leveraged mega-deals often fail spectacularly. However, consistent, smaller "bolt-on" acquisitions made by companies like Heico or Roper are highly successful but receive little media attention, skewing our perception.

Related Insights
The "buy-and-build" strategy has become the dominant model in private equity, especially in the middle market. Add-ons make up a staggering 75% of deal count, though only 40% of value. This shows a fundamental shift towards using smaller, bolt-on acquisitions as the primary method for deploying capital.

Blackstone's successful acquisition strategy focused on buying smaller, sub-scale businesses they could grow significantly. They avoided paying for fully built-out franchises, ensuring the value created by future growth accrued to their own shareholders, not the seller's.

While add-on acquisitions now represent 80% of PE deals, they are a crutch in software. Integrating disparate tech stacks is incredibly difficult and often deferred, leaving a mess for the next buyer. True value comes from strategic 'feature' acquisitions that can be deeply integrated into a core platform, not from rolling up unrelated businesses.
Acquiring smaller companies at a 5-6x EBITDA multiple and integrating them to reach a larger scale allows you to sell the combined entity at a 10-12x multiple. This multiple expansion is a powerful, often overlooked financial driver of M&A strategies, creating value almost overnight.
Peter Beck cautions that acquisitions are deceptively difficult. Like a polished used car, an acquired company looks great initially, but hidden issues only surface post-deal. Even small acquisitions can consume vast amounts of time to integrate financials, culture, and fix unforeseen problems.

The current M&A landscape is defined by a valuation disparity where smaller companies trade at a discount to larger ones. This creates a clear strategic incentive for large corporations to drive growth by acquiring smaller, more affordable competitors.

Successful M&A isn't about buying pristine assets, which offer no price advantage. Commure acquires companies with great distribution but specific, fixable problems (like a slow engineering culture), then rapidly expands their own products through the new channels.
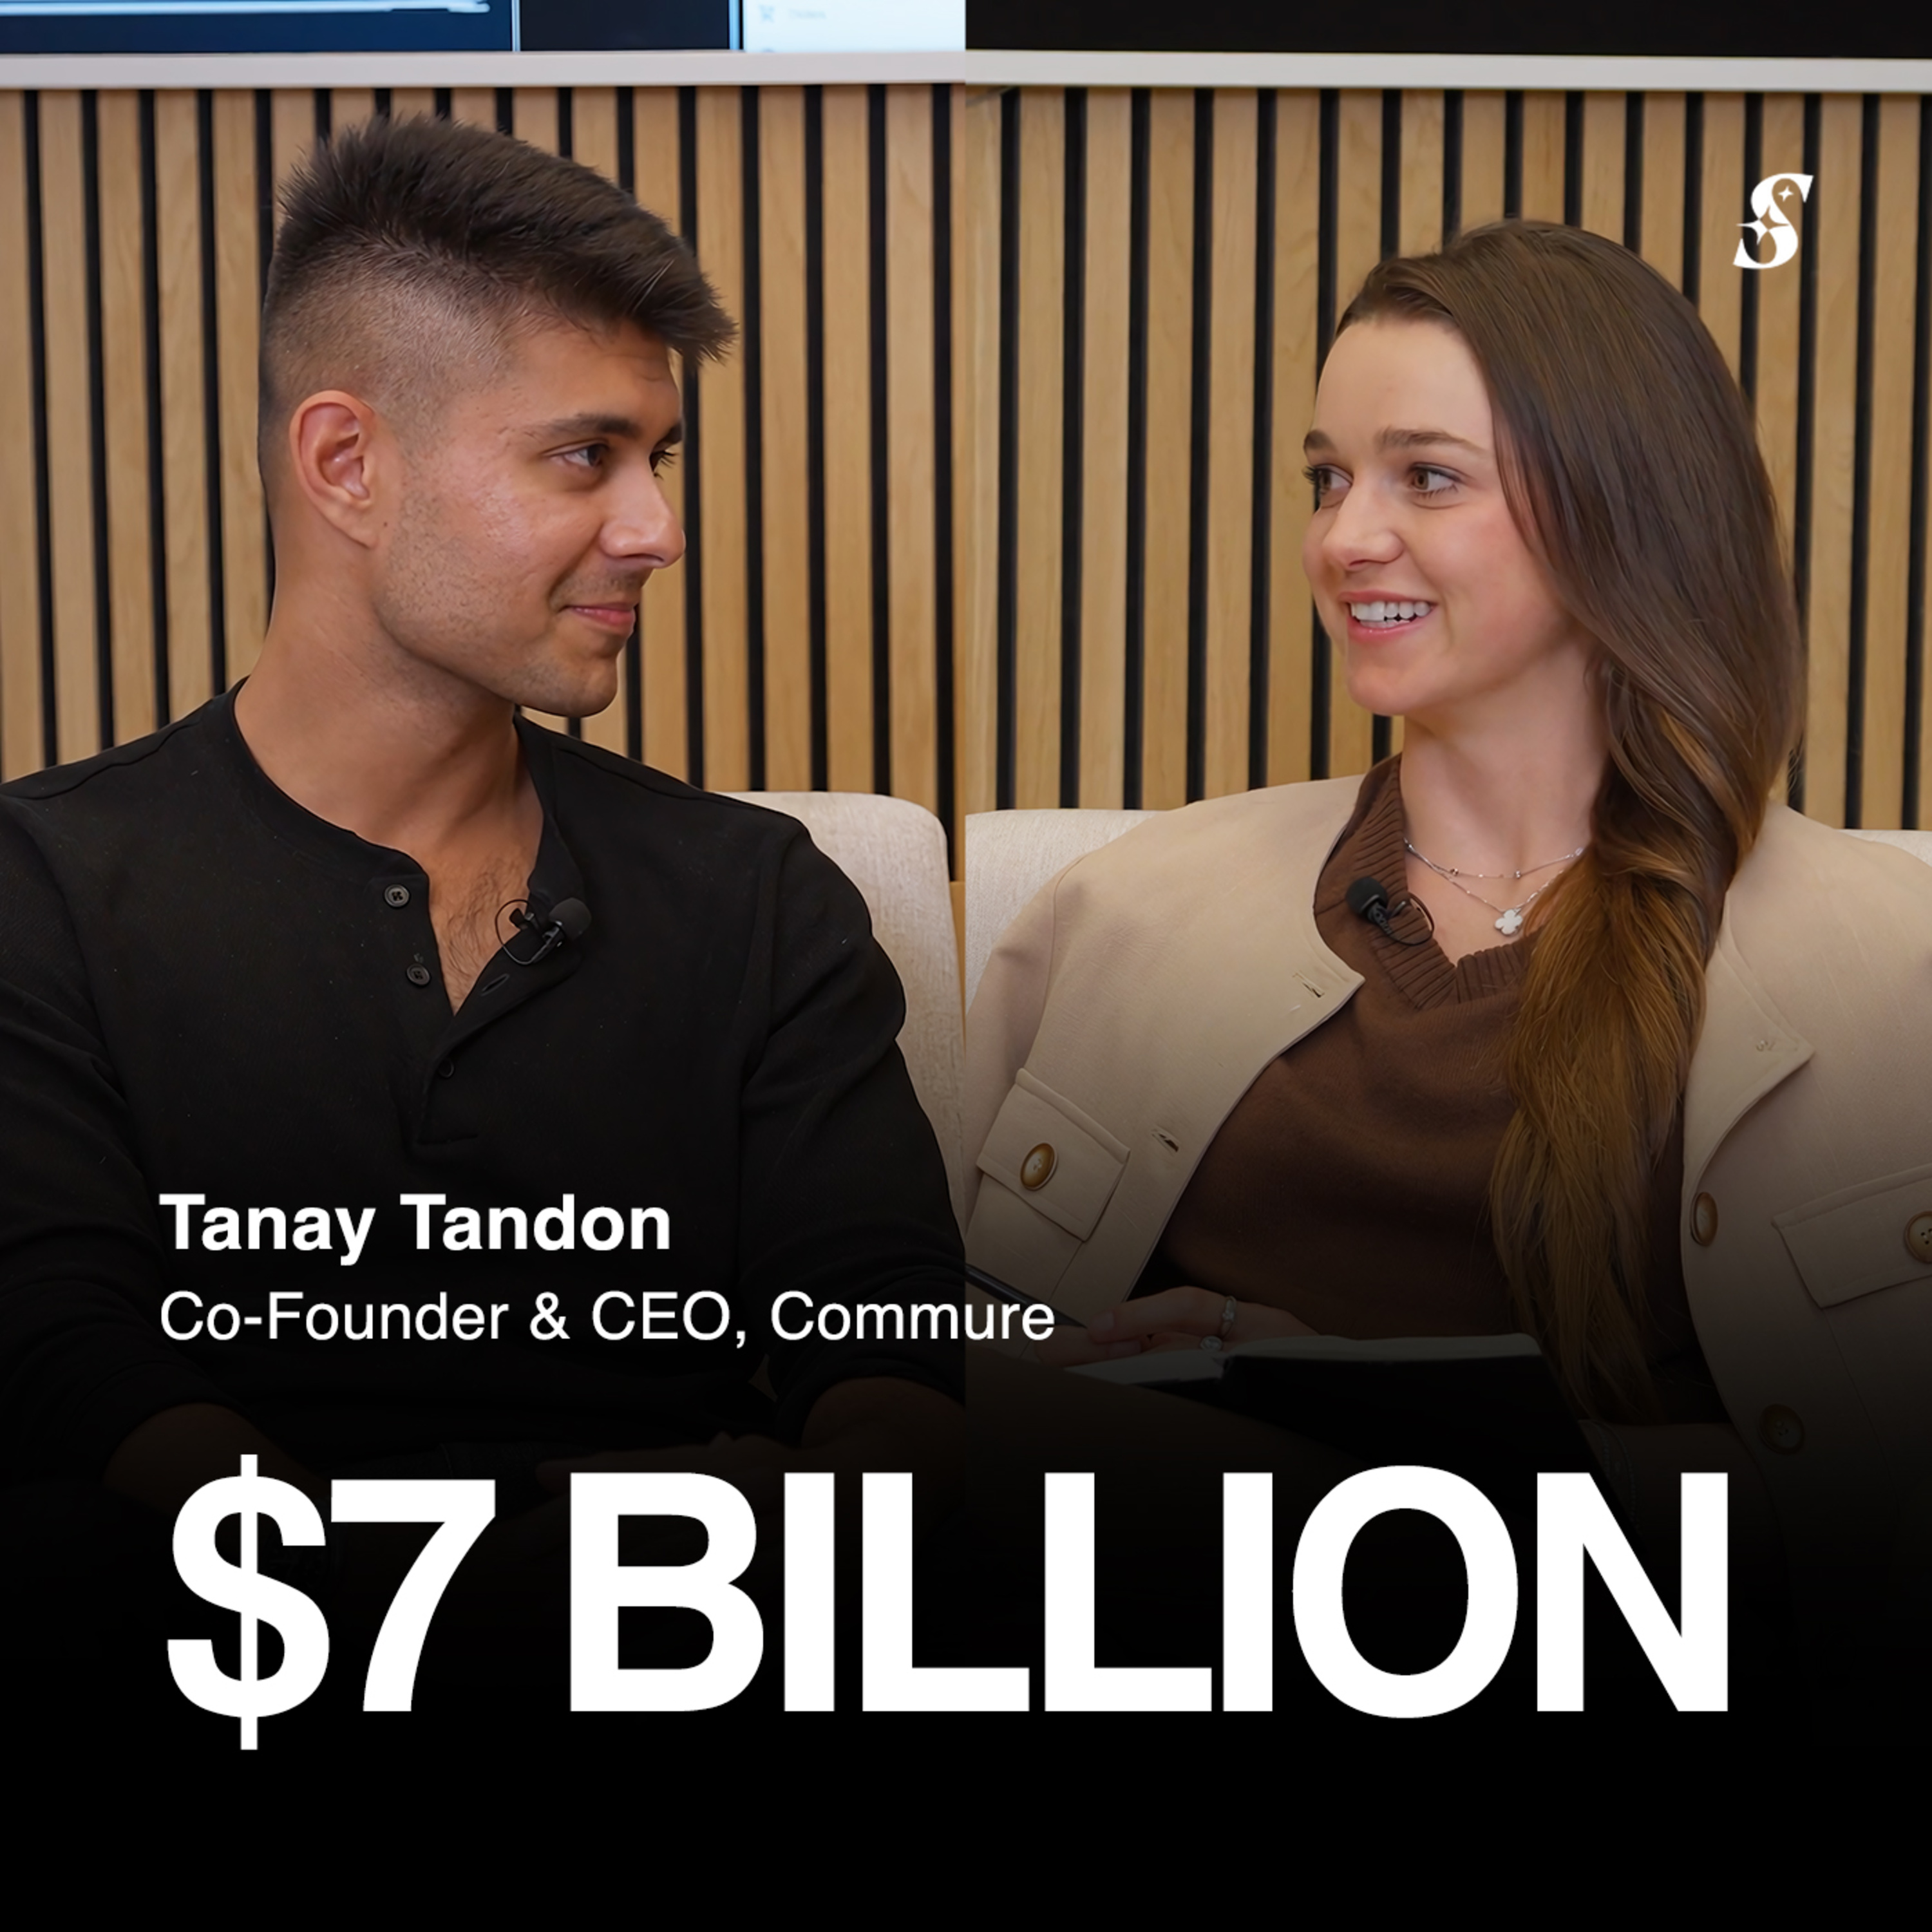
Viewing acquisitions as "consolidations" rather than "roll-ups" shifts focus from simply aggregating EBITDA to strategically integrating culture and operations. This builds a cohesive company that drives incremental organic growth—the true source of value—rather than just relying on multiple arbitrage from increased scale.

After making 13 acquisitions, Deel's CEO learned that the deals that didn't work well were those approached with a 'why not?' attitude. These were often opportunistic plays on adjacent but non-core businesses. Now, he has a simple filter: if an inbound acquisition opportunity isn't an immediate and enthusiastic 'hell yeah,' he passes, avoiding the distraction and integration challenges.
Massive M&A deals for legacy media are backward-looking financial transactions based on past earnings. The truly transformative acquisitions (like Facebook buying Instagram) are smaller, forward-looking bets on future trends like user-generated content.