Get your free personalized podcast brief
We scan new podcasts and send you the top 5 insights daily.
The UK currently operates as the most fiscally centralised country in the G7, but upcoming budget measures may alter this structure. Expected announcements point toward allowing regional mayors to retain portions of local income tax revenues, establishing fiscal autonomy to stimulate regional growth.

Related Insights
Despite market concerns about a potential new Labour government's fiscal stance, any increase in borrowing is likely to be carefully managed. The strategy would focus additional borrowing on investment spending while potentially using tax increases, rather than debt, to reverse planned cuts in day-to-day government expenditures, aiming to avoid spooking bond markets.

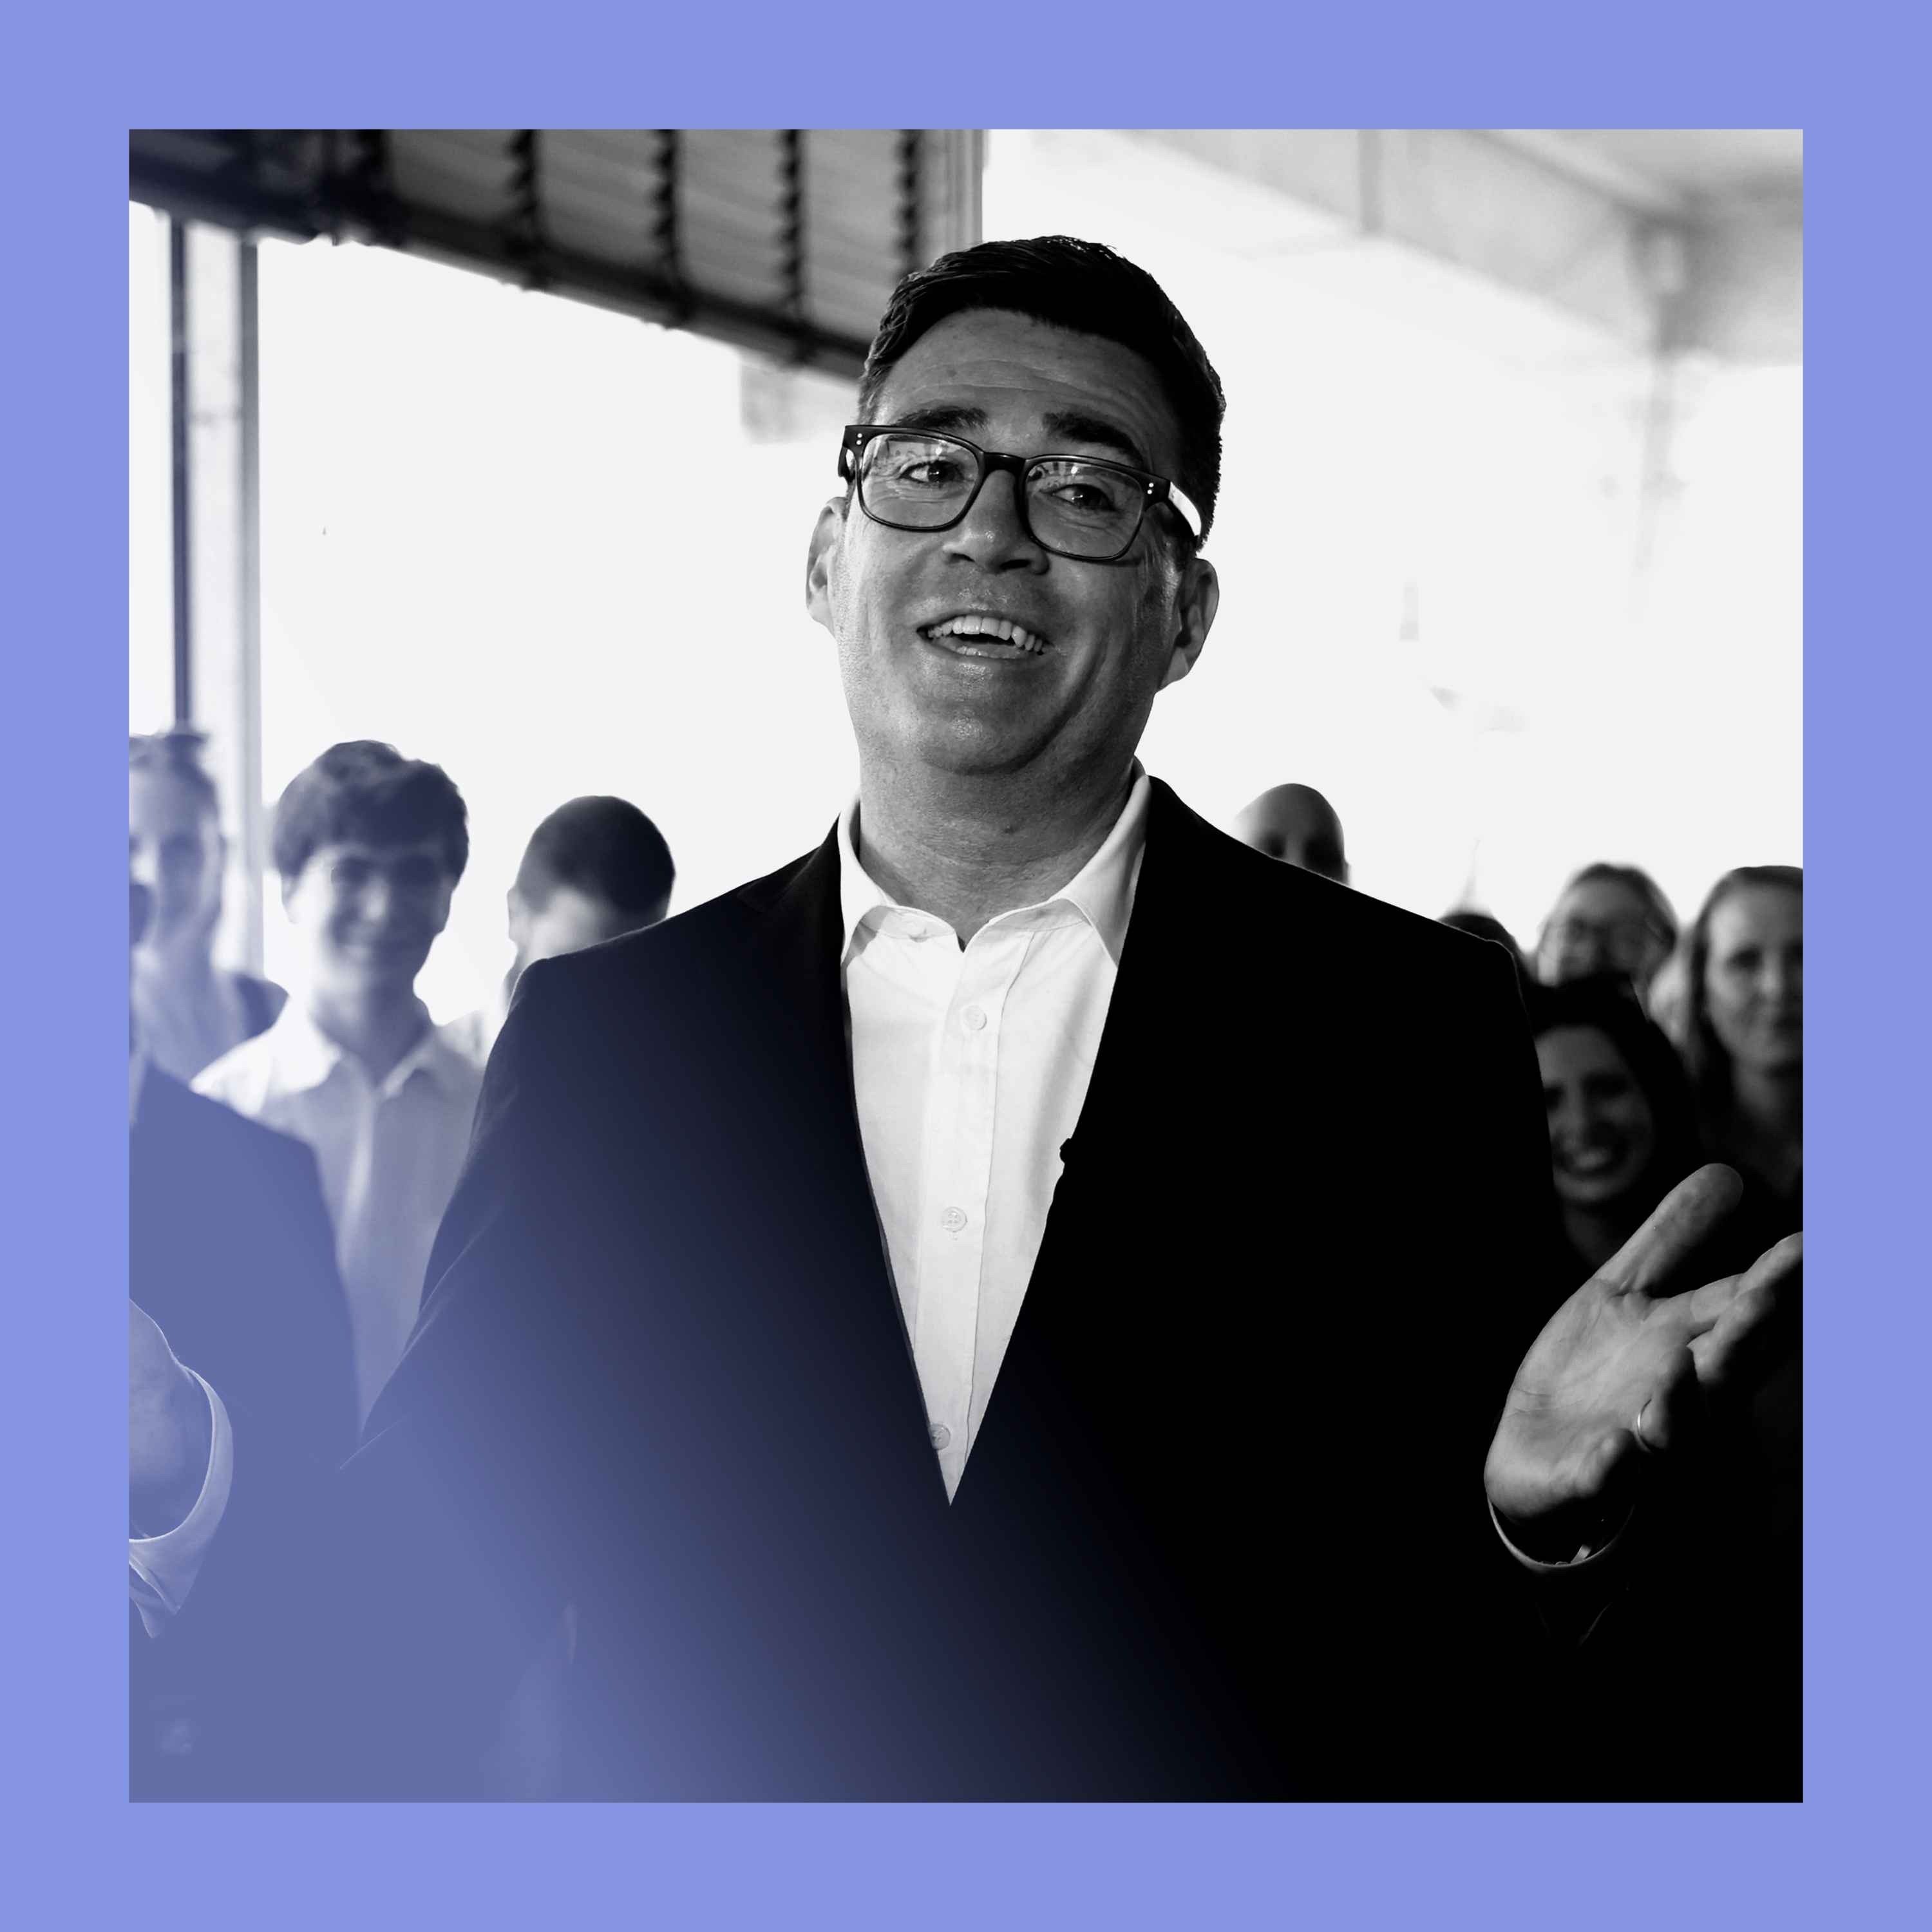
New PM Andy Burnham plans to split his Downing Street operation between London and a new "Number 10 North" in Manchester. This move physically manifests his core political promise to devolve power away from the capital, linking his regional brand ("King of the North") to a tangible, albeit controversial, national policy.
UK Sterling weakened despite news that personal income tax hikes might be avoided in the upcoming budget. This counterintuitive reaction, paired with rising Gilt yields, signals that investors are more concerned about the government's fiscal discipline and policy uncertainty than they are optimistic about potential short-term stimulus.
Market focus on the incoming UK Chancellor's identity is misplaced. The Prime Minister's overarching policy agenda will be the primary driver of fiscal direction. The Chancellor's role will be to implement that vision, making the leader's objectives more relevant for markets than the specific cabinet appointee.
Sterling's reaction to potential UK budget options is "any news is bad news." Even less-damaging proposals cause weakness because the market understands any policy will result in fiscal tightening, forcing the Bank of England to react dovishly.
Despite widespread perceptions of fiscal strain, the UK's primary deficit sits under 1% of GDP, noticeably lower than France at 2.9% and the US at 4.9%. The Treasury's three-year framework enforces current budget balance and targets a 1.5% primary surplus to reduce national debt-to-GDP.
While investors focus on high government debt, the UK is undergoing the most severe fiscal consolidation among G7 nations, according to IMF data. Medium-term plans target a deficit below 2% of GDP by 2030, a positive trajectory that seems mispriced by the market, given current high bond yields.
The UK's inability to build housing and infrastructure due to strict permitting, combined with a central government that disincentivizes local innovation, are identified as primary causes of its economic struggles, more so than Brexit itself.
UK markets have strongly priced in a specific budget result: significant income tax hikes and a major rebuild of fiscal headroom. This creates a risk that any deviation or a less aggressive fiscal consolidation could surprise investors and cause curve steepening.
The extreme concentration of economic output in dense urban areas is exemplified by London, which generates 70% of the UK's entire fiscal surplus. This highlights the critical role of cities as economic engines that financially support the rest of the nation.
